What Is Payment Orchestration? Everything You Need to Know
A comprehensive technical, financial, and operational guide to multi-processor payment architectures for scaling global enterprise brands.
Read Strategy
A comprehensive strategic, technical, and commercial breakdown of next-generation payment technologies shaping digital commerce.
The global payment ecosystem is undergoing a fundamental structural transformation driven by rapid technological innovation, shifting consumer expectations, and evolving regulatory frameworks. Standard digital checkouts that relied strictly on traditional credit card processing are fast becoming legacy infrastructure as merchants adopt frictionless, multi-rail financial architectures.
In 2026, staying ahead of digital payment trends is no longer just an operational detail—it is a core growth strategy. Emerging technologies like AI-driven hyper-personalization, open banking instant settlements, biometrics, and unified cross-border rails are redefining how value is exchanged across global digital channels, directly impacting customer acquisition, authorization performance, and processing overhead.
At TY ALPHA, TECHNOLOGY, we specialize in building fast, secure, and fully customized web development and payment infrastructure solutions. We have created this forward-looking strategic guide to give you an in-depth understanding of the key trends disrupting digital payments, their underlying technical mechanics, and how to future-proof your checkout architecture for maximum commercial agility.
If you need professional assistance preparing your payment stack for next-gen technologies, integrating real-time payment rails, or implementing friction-free checkout flows, our technical team is ready to help. Simply click the link at the bottom of the page to connect with our solution specialists.
Modern payment architectures are shifting from simple card-swipe models toward highly automated, intelligent, and real-time financial protocols:
Forward-thinking financial leaders no longer treat payment processing as an unavoidable administrative expense. Next-generation payment technologies allow enterprise brands to optimize operating margins while unlocking entirely new revenue streams.
By implementing intelligent payment orchestrators and adopting low-cost local rails (such as instant bank transfers and local digital wallets), businesses reduce overall unit processing costs. Furthermore, introducing contextual financing tools—such as embedded B2B micro-credit and hyper-localized Buy Now Pay Later (BNPL) schemes—directly increases average order value (AOV) and expands total addressable customer segments.
At TY ALPHA, TECHNOLOGY, we assist enterprise businesses in auditing payment conversion metrics, configuring modern checkout interfaces, and implementing modular payment stacks engineered for sustainable profit growth.
Evaluating the technical, financial, and customer-experience paradigm shifts reshaping payment architectures:
| Evaluation Dimension | Legacy Processing Stack | Next-Generation Payment Architecture |
|---|---|---|
| Settlement Speed | Delayed (T+2 to T+5 business days for bank settlement). | Instant Real-Time Settlement (sub-second or T+0 settlement). |
| Fee Structure | Fixed multi-tiered Interchange + Scheme + Markup costs. | Variable, low-cost A2A direct rail fees and micro-transaction tiers. |
| Authentication Mechanism | Manual card entry, static SMS OTPs, and basic 3DS prompts. | Passkeys, FIDO2 webauthn biometrics, and passive behavioral scoring. |
| Checkout Experience | Multi-step form inputs with high drop-off risks. | One-click biometrics, embedded contextual wallets, and AI auto-pay. |
| Cross-Border Efficiency | Expensive SWIFT routes with FX markups and correspondent fees. | Normalized local payment rails, multi-currency wallets, and digital rails. |
Building future-ready payment systems requires balancing advanced security compliance with ultra-fast frontend interaction speeds. Modern checkout architectures replace static card fields with biometric Passkeys (WebAuthn) and dynamically generated cryptographic tokens.
When a customer authorizes a purchase, the browser executes biometric authentication on-device via secure hardware modules (like Apple Touch ID / Face ID or Windows Hello). The client communicates with the server via encrypted REST APIs to request a single-use network token. This eliminates sensitive card numbers from crossing your servers, protects checkout flows against credential stuffing attacks, and guarantees native compliance with Strong Customer Authentication (SCA) mandates.
This modern cryptographic approach minimizes PCI DSS audit scopes while maximizing checkout speeds and transaction approval rates.
The checkout interface is evolving into a dynamic, personalized engagement engine.
Next-generation checkout platforms leverage real-time geolocation, device context, and historical customer profiles to dynamically display the buyer's absolute preferred payment method—whether that is a local instant bank transfer, a regional digital wallet, or biometrically secured 1-click checkout. Providing localized payment options dynamically boosts consumer trust and delivers conversion lift across global markets.
To transition your business from legacy payment gateways to a scalable, next-generation payment stack, we follow a structured 6-step engineering methodology:
Analyze current checkout drop-off points, transaction fee breakdowns, authorization performance, and regional payment method gaps.
Deploy independent tokenization microservices to decouple customer stored payment credentials from underlying processor platforms.
Implement FIDO2 WebAuthn standards to support 1-click biometric payments and frictionless SCA compliance across web and mobile browsers.
Connect direct A2A instant payment APIs and local digital wallet schemes to lower reliance on high-cost card processing networks.
Configure dynamic routing rules to direct transaction payloads across low-cost acquiring paths and automated fallback channels.
Deploy unified transaction reporting dashboards to monitor real-time authorization trends, settlement speeds, and fraud risk metrics.
Adopting the future of online payments enables your business to build frictionless, resilient, and ultra-scalable checkout architectures—driving conversion performance while keeping transaction costs under complete control.
Whether you are integrating real-time open banking rails, modernizing checkout user experience with biometric authentication, or deploying smart orchestration, our development team is ready to lead your project. The technical specialists at TY ALPHA, TECHNOLOGY excel at engineering lightning-fast, high-converting, and future-proof web payment solutions built for long-term commercial success.
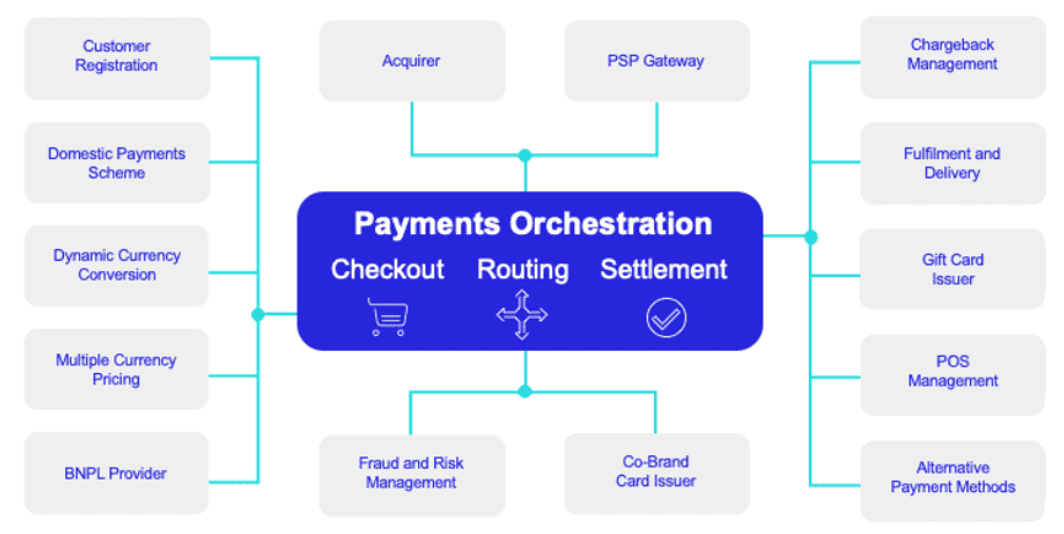
A comprehensive technical, financial, and operational guide to multi-processor payment architectures for scaling global enterprise brands.
Read Strategy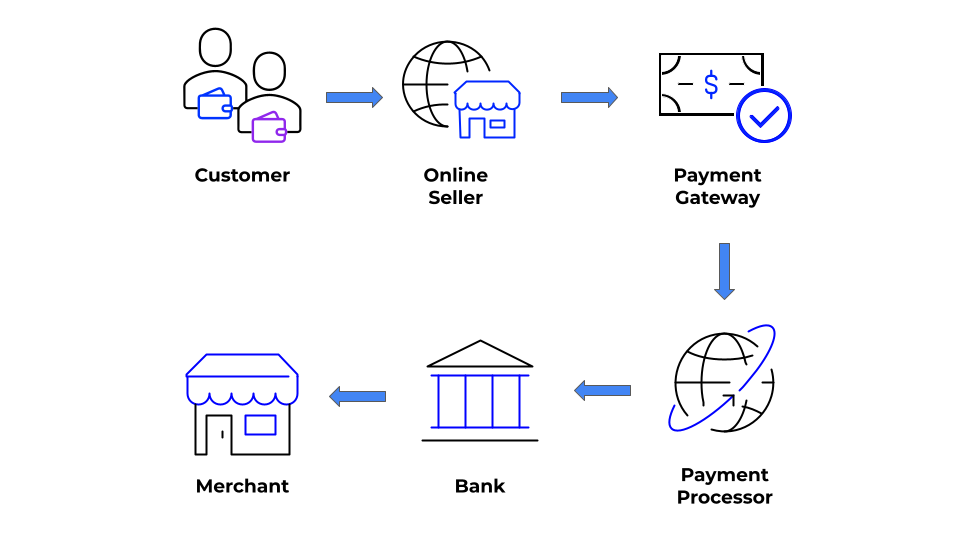
A comprehensive technical, financial, and operational guide to the data flows, authorization lifecycles, and security protocols powering digital transactions.
Read Strategy